Having land but no regular income: Can you apply for funding? What to know about mortgaging land without a salary slip.
Having land but no regular income, can you apply for funding by mortgaging the land? The answer is yes, there is a chance to do so even without a salary slip, but it does not guarantee approval. Lenders will consider the value of the land, ownership, obligations, verifiable income, and repayment plans.
Property owners who are self-employed, farmers, or business owners may not have a regular salary but still have actual income from their work.
Therefore, the important thing is not just having a salary slip but demonstrating how the borrowed money will be used and where the repayment will come from. Why is it that someone can have land worth millions but still cannot apply for funding?
Consider a landowner who has land valued at around 5 million baht, has no debts attached to the title, and wants funding of 2 million baht.
From the property owner's perspective, the land is worth 2.5 times more than the amount needed, so they may feel that the collateral is sufficient.
However, the lender must think from another angle.
If they lend 2 million baht, where will the property owner get the money to pay interest and repay the principal?
If the property owner has no income at all, even if the land is highly valued, the lender may not approve the loan.
The reason is that mortgaging is not intended for creditors to sell the land when the borrower defaults.
Repayment from regular income should be the primary source of repayment, while the land serves as collateral in case of problems.
This concept aligns with the Bank of Thailand's responsible lending principles, which emphasize repayment ability and preventing over-indebtedness.
Not having a salary slip does not mean having no income.
Many people in Thailand do not receive a regular salary. Bank of Thailand
For example, farmers earn income from selling produce twice a year.
Shop owners may have daily income but do not pay themselves a salary.
Contractors may receive payments based on work milestones.
Self-employed individuals may have high income in some months and low in others.
These individuals do not necessarily lack the ability to repay loans, but they need evidence to help lenders assess their actual income.
What types of income can be considered?
Examples of evidence that may be used for assessment include bank statements, receipts, work contracts, sales documents, customer payment records, or tax documents.
For farmers, sales data and cultivation expenses may be used.
For business owners, sales figures, cost of goods, operating expenses, and net cash flow may be used.
However, each lender has different criteria.
Having these documents does not guarantee approval but helps clarify repayment ability.
When mortgaging land without a salary slip, LTV must also be considered.
LTV or Loan-to-Value Ratio is the proportion of the loan amount compared to the value of the collateral.
For example, if the land is valued at 5 million baht and the desired funding is 2 million baht, the LTV is 40%.
If the desired funding is 3 million baht, the LTV will increase to 60%.
However, the LTV figure alone is not sufficient for approval.
This is because the value of the land may vary depending on the assessment method.
Land in areas with many buyers may sell more easily than land in remote areas.
2,000,000 ÷ 5,000,000 × 100 = 40%
Land without legal access may have usage limitations.
Land with encumbrances or disputes may also carry additional risks.
Property owners who want to understand the principles of loan amount assessment can read articles like 'Mortgaging 3 Million Baht at 12% Annual Interest: How Much to Pay?' to study the relationship between loan amounts, costs, and repayment ability.
What do lenders look at besides land price?
Lenders who manage risk carefully often consider several factors together.
The first is ownership.
It must be verified whether the property owner has the right to mortgage the land. The second is obligations. If the land is already mortgaged, the outstanding debt and the order of creditor rights must be checked.
The third is the liquidity of the asset.
If the land needs to be sold, will there be buyers, and how long might it take?
The fourth is the borrower's income and debt obligations.
The last is the repayment plan for the principal.
Some property owners can pay monthly interest but have no plan to repay the principal when due.
This is a risk that should not be overlooked.
Case Study: A Farmer with 5 Million Baht Land, No Salary, Wants to Mortgage 2 Million Baht.
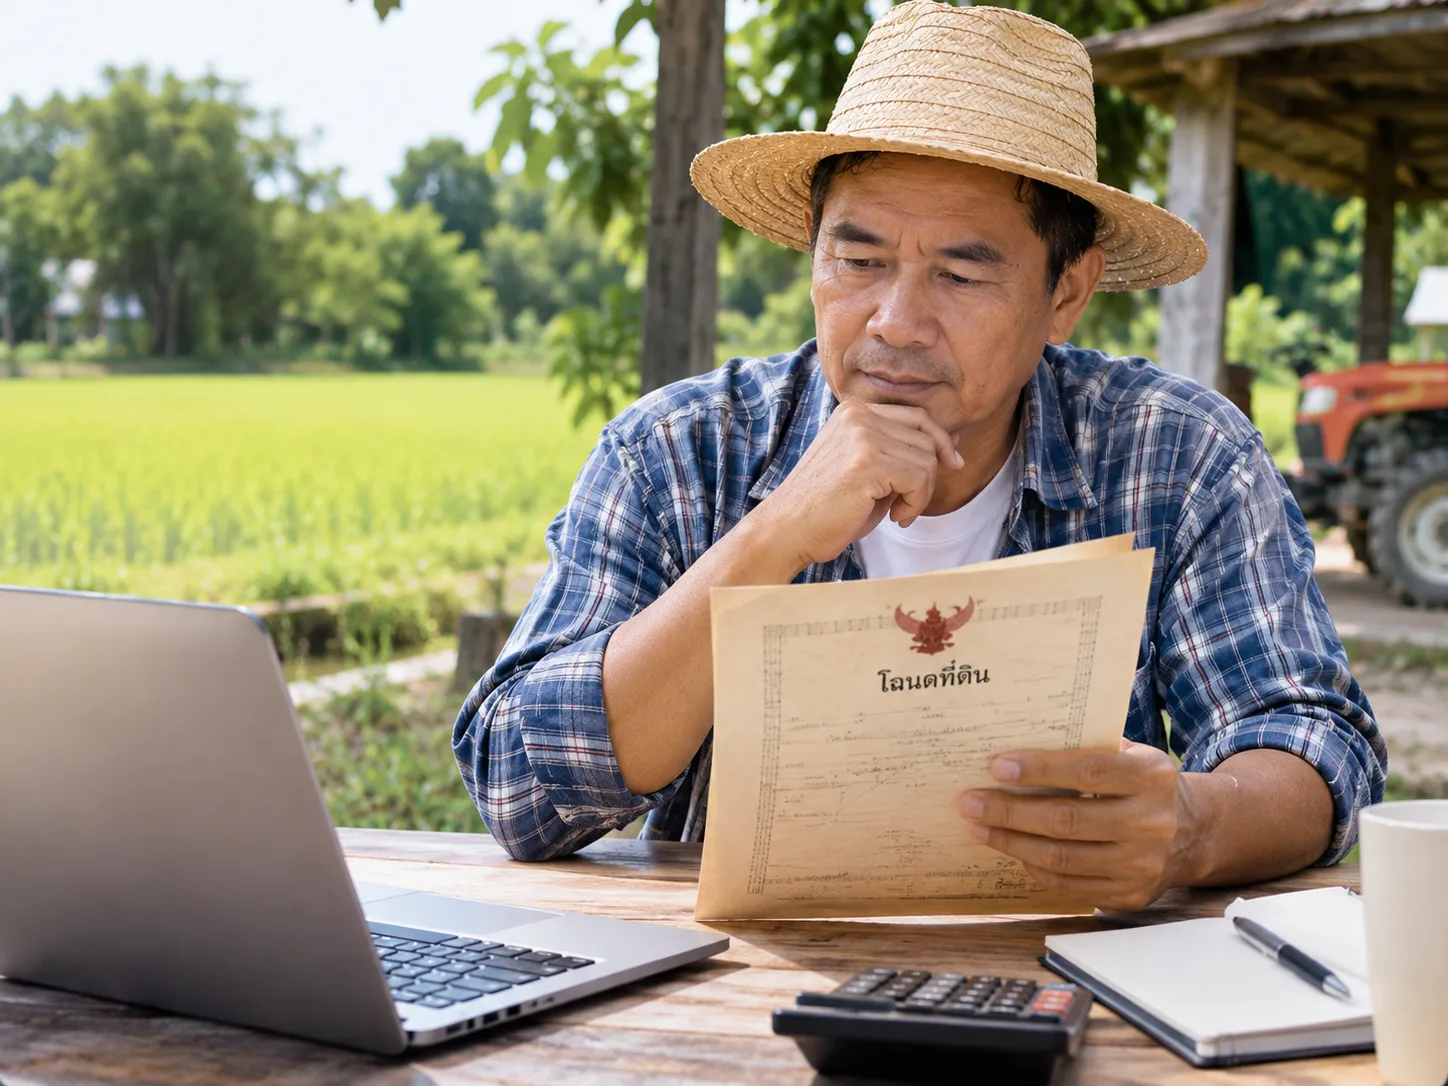
Suppose Mr. A is a farmer with land valued at around 5 million baht.
He has no salary slip but has income from selling produce and contract work.
He wants 2 million baht in funding to invest in irrigation systems and buy agricultural equipment.
Assuming he has an average income of 100,000 baht per month and total operating and household expenses of 60,000 baht.
นี่เป็นความเสี่ยงที่ไม่ควรมองข้าม
กรณีศึกษา: เกษตรกรมีที่ดิน 5 ล้านบาท ไม่มีเงินเดือน ต้องการจำนอง 2 ล้านบาท
สมมตินาย ก. เป็นเกษตรกร มีที่ดินมูลค่าตลาดประมาณ 5 ล้านบาท
ไม่มีสลิปเงินเดือน แต่มีรายได้จากการขายผลผลิตและงานรับจ้าง
ต้องการเงินทุน 2 ล้านบาทเพื่อนำไปลงทุนในระบบน้ำและซื้ออุปกรณ์การเกษตร
สมมติว่ามีรายได้เฉลี่ย 100,000 บาทต่อเดือน และมีค่าใช้จ่ายดำเนินงานกับครัวเรือนรวม 60,000 บาท
This leaves an average cash flow of 40,000 baht per month before new debt repayment.
To compare costs, assume a lender under general lending laws offers an interest rate of 12% per annum, calculated on a fixed principal and paid monthly.
This rate is merely a hypothesis for the study and does not represent an actual offer or guarantee the legality of all terms.
Table analyzing capital and debt repayment capacity
| Item | Amount |
|---|---|
| Assumed land value | 5,000,000 baht |
| Desired mortgage amount | 2,000,000 baht |
| LTV | 40% |
| Assumed interest at 12% per annum | 240,000 baht |
| Average monthly interest | 20,000 baht |
| Assumed initial expenses | 20,000 baht |
| Net income | 1,980,000 baht |
| Average monthly income | 100,000 baht |
| Monthly expenses | 60,000 baht |
| Remaining funds before new debt repayment | 40,000 baht |
| Remaining funds after paying interest | 20,000 baht |
| Principal to be repaid at the end of the year | 2,000,000 baht |
The numbers can be verified as follows:
LTV = 2,000,000 ÷ 5,000,000 = 40%
Annual interest = 2,000,000 × 12% = 240,000 baht
Average monthly interest = 240,000 ÷ 12 = 20,000 baht
Net income = 2,000,000 − 20,000 = 1,980,000 baht
Remaining funds after paying interest = 40,000 − 20,000 = 20,000 baht per month
If this amount is saved for 12 months, there will be 240,000 baht.
However, the principal of 2 million baht still needs to be repaid.
The hidden problem in the numbers
If only looking at monthly income, Mr. A may be able to pay the interest.
But if at the end of the year he has to repay the entire principal, he still does not have enough money.
Even if he uses the accumulated 240,000 baht to pay the principal, he will still be short by 1,760,000 baht.
Therefore, investors should ask how much additional income the water system investment will generate and when it will be received.
Without a credible plan for repaying the principal, it may be necessary to reduce the loan amount, adjust the repayment format, or consider other options.
The land valued at 5 million baht helps reduce collateral risk but does not eliminate cash flow risk.
If there is no income at all, can the land be mortgaged?
The case of having no regular income versus having no income at all is very different.
Those without a salary but may have income from rent, trade, or agriculture can still use that information for consideration.
However, those without income and no clear repayment source will have higher risks.
Even with valuable land, lenders may refuse.
Because lending with the hope of selling the land upon default is not a suitable risk management approach.
Property owners should consider whether they really need to borrow.
If there is no income to repay the debt, selling part of the property or finding business partners may be alternatives to consider.
However, selling property will affect ownership, and joint ventures have their own risks and conditions.
Which is more suitable for people without regular income: mortgaging land or selling it?
Both transactions have different legal implications.
Mortgaging involves using the property as collateral while ownership remains with the property owner.
If the debtor defaults, the creditor must proceed with foreclosure according to the law, rather than immediately acquiring ownership of the land.
On the other hand, selling with a right of redemption transfers ownership to the buyer from the registration date, with the seller having the right to redeem under the conditions and time frame set by law.
Those without regular income must be especially cautious.
Without a redemption plan, selling with a right of redemption may risk losing the property.
For agricultural or residential land that meets the criteria of the People's Protection Act for contracts of sale with a right of redemption for agricultural or residential land, one must also consider the rights and limitations under specific laws.
Interested parties can read more from Steps for Selling Land Before Money Enters the Account To understand the steps before conducting a transaction
What should property owners prepare if they do not have a payslip?
The first thing is property information
You should have a clear land title or a copy, along with details of the location, size, and usage condition
The second thing is past income information
If you are a farmer, you should gather evidence of product sales
If you are a contractor, you should prepare contracts and evidence of payment received
If you are a business owner, you should prepare bank statements, sales figures, and expenses
The third thing is all debt obligations
You should not only disclose debts related to the land title but also reveal obligations that affect repayment ability
The last thing is the plan for using the money and the plan for repaying the principal
If you need money for investment, you should explain when the investment will generate income and what risks are involved
How can mortgage brokers assist clients without a payslip?
A good broker should start by understanding the property owner's situation
They should not promise that having a land title guarantees money
They should help organize income and expense information for lenders to consider more easily
If it is found that the client cannot repay the debt, they should explain the risks honestly
They should not pressure clients to sign contracts just to earn a commission
If there is a broker fee, it should be disclosed who pays it, how much, and when, as well as checking for legal compliance
Working transparently helps build trust with both property owners and investors
Should investors accept deals without a payslip?
Investors should not use the presence or absence of a payslip as the sole criterion
Some self-employed individuals may have good cash flow and a consistent repayment history
Conversely, salaried employees may have high debt burdens that prevent them from taking on more debt
Therefore, assessments should consider net income, income consistency, debt obligations, and collateral together
For seasonal income, cash flow should be assessed based on actual income cycles, not by dividing annual income by 12 and assuming money comes in every month
If income is uncertain, there may need to be reserves or a repayment structure aligned with income
However, the conditions must comply with relevant laws
How should interest and fees be checked?
Those without regular income may receive funding offers with higher costs than expected
Before signing a contract, you should request written details of the principal, interest, fees, commissions, and net amount
For loans between individuals, the Civil and Commercial Code, Section 654, should be considered, which generally limits interest to no more than 15% per year, and the law prohibits charging interest above this rate
Some service providers may be subject to specific laws with different criteria
Charging fees for processing or other services does not automatically make the charges legal
If the fees have the nature of hidden interest, the costs and legal limitations should be considered together
You should not cite market rates as rates permitted by law
What should be done if funding is not approved?
Property owners should ask for the reasons for the denial as much as the lender can disclose
If it is a documentation issue, they may improve data collection for clarity
If it is a problem of excessive loan amount, they may reduce the amount needed
If it is a cash flow issue, they should review the business plan or sources of debt repayment
If it is a liquidity issue of the land, they may need to consider other options
You should not rush to switch from mortgage to selling without understanding the impact on ownership
Those considering selling property instead of incurring more debt can study the PK HOME INVEST real estate listing system to see channels for listing properties, noting that listing does not guarantee a sale or timely sale
In summary: No regular salary does not close the door on land mortgages
Property owners without a payslip may still have opportunities to request funding through land mortgages
But they must demonstrate reliable income or repayment sources
Having high-value land helps with collateral but does not replace repayment ability
Brokers should help organize information and disclose conditions transparently
Investors should assess both property value and cash flow
A good mortgage deal is not one where the property owner receives the most money, but one where the property owner has the opportunity to use the money and repay it effectively
If you want to learn more, you can follow Facebook PK HOME INVEST and check contact channels on the website before submitting personal documents or conducting transactions
Frequently Asked Questions
1. Can I mortgage land without a payslip?
It is possible if the lender accepts other forms of income evidence and assesses that there is sufficient ability to repay the debt, but there is no guarantee of approval.
2. If there is land worth 5 million baht but no income at all, can I borrow 2 million baht?
It cannot be concluded solely from the value of the land. The lender must consider the sources of repayment and other risks as well. If there is no credible repayment plan, approval may not be granted.
3. Can farmers use income from selling produce instead of a salary slip?
It may be used as supporting evidence depending on the lender's conditions. It is advisable to prepare evidence of income, expenses, and production cycle information.
4. If there is no regular income, should I choose to mortgage or sell with a buy-back option?
You must carefully compare ownership, costs, and repayment or redemption plans. Selling with a buy-back option carries the risk of losing ownership if not redeemed according to the law, so it should not be chosen solely for quick cash.
References and considerations before publication
Bank of Thailand — Responsible Lending
Explains the principles of responsible lending, assessing repayment ability, and preventing over-indebtedness issues.
The role of Responsible Lending in sustainable debt resolution
Bank of Thailand — Household Debt Relief Measures
Explains lending approaches that consider repayment ability and debtor protection.
Civil and Commercial Code
Used to examine mortgage principles under Section 702 and interest rate limitations under Section 654.
Civil and Commercial Code information from government agencies
Considerations before publication: The case study table is hypothetical and not an actual loan offer from PK HOME INVEST. Initial costs and interest rates must be verified according to the type of lender and applicable laws before being presented to customers, and mortgage transactions must be clearly separated from buy-back sales.